

Table of Contents
Ask any self-employed Australian or business owner about getting a self employed home loan Australia wide, and they will likely tell you the same frustrating story. They are highly profitable, running a fantastic operation, and managing strong monthly cash flow—but because they haven’t compiled two full years of traditional company tax assessments yet, the mainstream lenders refuse to look at them.
The traditional lending landscape moves at a glacial pace. It relies on backward-looking data, punishing entrepreneurs, contractors, and tradies who have short business runways but strong current performance. When a major lender insists on seeing pristine, multi-year company tax returns, a self-employed client’s property dream stalls. For their mortgage broker, it usually means a dead pipeline file.
But the modern workforce is changing. Top-tier originators are realising they no longer must wait two years to write a winning deal. By pivoting to alternative documentation (alt-doc) solutions, brokers are successfully moving self-employed scenarios away from automated lending matrices and turning toward human underwriting.
Key Takeaways
- Self-employed home loans Australia are highly accessible without the standard two-year trading history requirement.
- Specialist credit providers use Alt-Doc solutions (like 2 recent BAS and business account statements) to verify real-time cash flow and bypass automated rejections.
- Human underwriting looks beyond strict algorithms, valuing industry continuity and actual asset positions over the age of an ABN.
- Active ATO payment plans or tax debts do not mean an automatic decline; they can be consolidated into a manageable residential mortgage.
The Structural Flaw of Traditional Self-Employed Assessment
Mainstream lenders assess self-employed income by looking at historical tax returns, usually averaging the last two years or taking the lower of the two. While this system functions for established corporations, it is fundamentally flawed for a growing small business.
This rigid framework ignores critical qualitative factors, including:
- Lagging Indicators: Tax returns represent the past, not the current trading reality of a scaling enterprise.
- The Tax Minimisation Penalty: A successful business owner may genuinely earn strong cash profit, but after depreciation write-offs, vehicle expenses, and legitimate business deductions, their taxable income as reported to the ATO appears artificially low.
- The “Too New” Decline: If a borrower has transitioned from PAYG to self-employment within the same industry and only holds an ABN for 8 to 12 months, automated institutional matrices will issue an automatic system decline, completely ignoring the applicant’s prior industry experience.
Consider the standard asset write-offs or aggressive depreciation schedules utilised by smart commercial accountants. A self-employed tradesperson or business owner might purchase a $60,000 commercial vehicle or invest in heavy machinery to expand their operations, writing the cost off to legally minimise their immediate tax burden.
On a traditional lender’s automated scorecard, this strategic business move artificially tanks their taxable income, making it appear as though the applicant cannot service a loan.
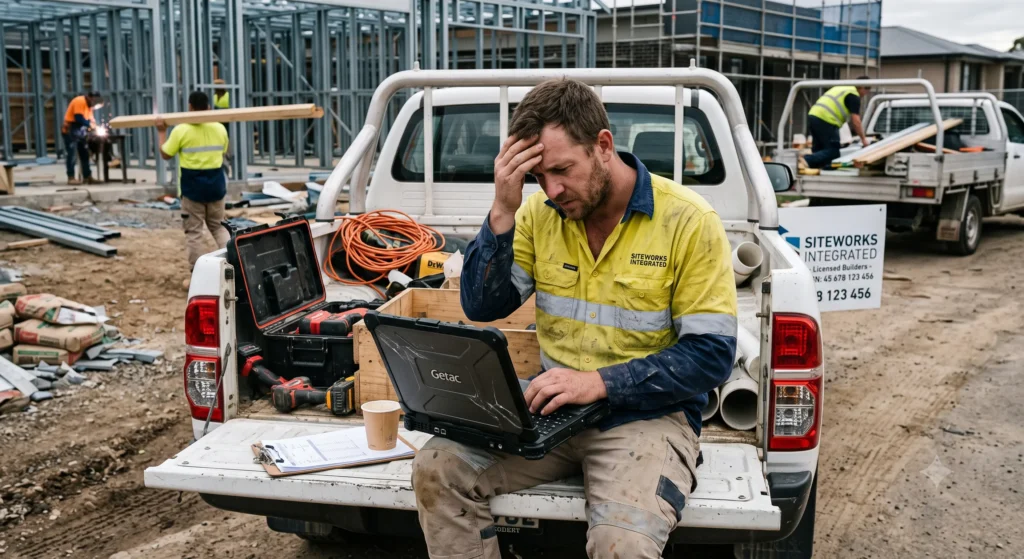
A human underwriter, however, identifies this as a one-off capital expense. They can add that depreciation back into the servicing calculator, revealing the true, robust health of the underlying business cash flow.
The reliance on these backward-looking matrices by mainstream institutions is partly a byproduct of how they manage volume under the National Consumer Credit Protection Act (NCCP Act). While strict responsible lending obligations are non-negotiable, major lenders program their compliance software to automatically reject any self-employed application displaying a limited history, rather than investing the manual hours required to verify the actual cash flow.
Our Flexi Business Plus product allows brokers to bypass the automated decline entirely.
Alt-Doc Solutions: No Tax Returns Required
When traditional documentation fails, alternative documentation (alt-doc) pathways step in to bridge the gap. By completely eliminating the requirement for outdated tax files, savvy brokers can keep their deals moving forward using real-time operational indicators.
Unlike traditional low-doc home loans which still require some tax documentation, VMG’s Alt-Doc solutions require no tax returns, just 6 months of ABN registration, two recent BAS that must be consecutive and from the same financial year, and business bank statements to verify real-time servicing capacity. This structural shift allows brokers to bypass the automated decline entirely.
Case Study Breakdown: Supporting a $750,000 Self-Employed Purchase
To see the tangible value of alt-doc solutions over traditional tax assessments, we can examine a real-world scenario recently processed via our specialised alternative lending pathway.
A self-employed borrower had found the perfect owner-occupied property and sought financial assistance for a $750,000 loan amount. The business was thriving, the revenue was highly consistent, and the borrower possessed a strong deposit.

The Operational Challenge
The applicant had recently transitioned from PAYG employment to self-employment within the exact same industry. The fatal flaw for traditional lenders? The applicant’s ABN had only been registered for 8 months.
They simply did not have the historical two-year tax file footprint that automated mainstream credit matrices strictly demand. Under standard institutional criteria, this file is an automatic system decline. The business is deemed “too new,” and the client is turned away. For a purely transactional broker, this deal would have been abandoned.
The 2 BAS Solution (The Human Underwriting Intervention)
Instead of letting a profitable file go to waste, the originating broker bypassed the standard tax assessment rules entirely and presented the scenario* directly to the team at Victorian Mortgage Group (VMG).
Rather than forcing the client to fit into an old-school financial box, our human underwriting team stepped in to review the business’s real-time trading health. Because the applicant had transitioned from PAYG to self-employment within the same industry, their continuity of experience mitigated the risk of the new ABN.
The Dual-Sided Resolution
VMG assessed the applicant’s actual business performance. By analysing the day-to-day cash flowing through the business accounts, the underwriter demonstrated the borrower’s true servicing capacity with absolute certainty.
The result for the broker? A highly profitable self-employed file rescued from the “too hard” basket, establishing a long-term referral pipeline with a growing SME.
The result for the client? Approved for their home without having to wait another 18 months for arbitrary institutional tax cycles to close.
Timeline to Approval
File paused for 12+ months waiting on financial year rollover…
Income verified via real-time trading cash flow.
Valuing Industry Continuity Over ABN Age
One of the most critical elements our human credit analysts evaluated in this scenario was the exact nature of the applicant’s transition. Moving from a PAYG employee to a self-employed contractor within the exact same industry does not erase an applicant’s underlying skill set, client network, or earning capacity.
While an institutional algorithm resets their ‘experience clock’ to zero on the day the new ABN is registered, manual underwriting recognises the continuity of their career. By evaluating their prior PAYG history alongside their fresh business banking statements, we established a clear, uninterrupted trajectory of income generation that completely mitigated the risk of the 8-month-old ABN.
Instead of waiting for lagging tax returns, the credit team accepted alternative verification:
- 2 x Consecutive Business Activity Statements (BAS) from the same financial year
- Management accounts for the business
- 6 months of banking statements
The 3-Step Alt-Doc Verification Pathway
6 Months ABN Registration
The minimum trading history required to initiate a manual assessment.
2 Recent Consecutive BAS
Must be consecutive and fall within the exact same financial year.
Business Account Statements
Six months of clean transaction histories to verify real-time cash flow.
Unlocking the Self-Employed Market
With self-employed Australians increasingly turning to the broker channel, driving the Mortgage and Finance Association of Australia (MFAA) market share to record highs, the demand for flexible verification is peaking. Concurrently, the Australian Prudential Regulation Authority (APRA) mandates strict historical verification protocols for mainstream lenders. VMG’s alt-doc underwriting provides a vital alternative; because it is not bound by the exact same restrictive historical tax-return matrices, credit managers can assess alternative income verification efficiently and safely.
Whether your client is purchasing a new home, accessing equity to expand their operations, or consolidating ATO tax debts, alternative documentation provides a clear path forward.
Optimising Your Brokerage for Alt-Doc Scenarios
To keep growing your asset pipeline, it is essential to adjust how you handle self-employed applications.
- Identify the True Cash Flow: Look beyond the taxable income. Request 6 months of business bank statements early to understand the actual cash moving through the operation.
- Leverage Industry Continuity: If a client just started their own ABN but has years of PAYG experience in the exact same trade, that story matters to a human underwriter.
- Partner with Verified Non-conforming Specialists: Build reliable relationships with lenders who offer flexible 2 BAS or accountant declaration policies, ensuring you always have a solution for clients with limited business history.
- Master the Management Accounts Narrative: Summarise interim P&Ls and balance sheets rather than just handing over raw files. Highlighting consistent deposits and isolating one-off setup expenses help human underwriters instantly validate the deal.
🛠️ The Alt-Doc File Packaging Blueprint
Once you have optimised your approach, here is how you should physically package the file to ensure a rapid, common-sense manual assessment.
1. The Narrative
Draft a comprehensive cover letter detailing the client’s transition from PAYG to ABN within the exact same industry. Context is critical for a human credit analyst.
2. The Evidence
Bypass the tax return requirement by attaching exactly two recent, consecutive BAS statements alongside six months of clean business transaction histories.
3. The Context
Provide interim P&Ls with clear annotations for any one-off capital expenses (e.g., heavy machinery or vehicle purchases) so the underwriter can easily add them back to the servicing calculator.
Accelerate Your Self-Employed Approvals
You don’t need to tell a profitable client to wait another 12 to 24 months to buy a house. If you are still relying entirely on traditional institutional matrices to assess your self-employed clients, you are leaving viable commissions on the table.
Connect directly with a VMG Human Underwriter today to pitch your client’s unique self-employed scenario live, or book a call with your local BDM to start expanding your alt-doc lending options.
Frequently Asked Questions
Q: How long do you need to be self-employed to get a home loan in Australia?
Q: What is an alt-doc home loan?
Q: Can I get a home loan with only 2 BAS statements?
Q: Does buying commercial equipment or a work vehicle ruin my chances of getting a home loan?
Q: Will my previous PAYG experience help if I recently registered a new ABN?
*All applications are subject to Victorian Mortgage Group’s standard credit assessment and lending criteria. Terms, conditions, fees, and charges apply.