
Table of Contents
- What Is Non-Conforming Lending?
- Mainstream Lenders vs Specialist Lenders: Understanding the Divide
- Lending Criteria Comparator
- Dispelling the Myths of Non-Conforming Finance
- Why the Interest Rates Reflect the Assessment Work
- 6 Client Profiles VMG Actually Helps
- What Makes VMG Different?
- The Most Important Mindset Shift for Brokers
- Frequently Asked Questions
What Is Non-Conforming Lending?
At its core, non-conforming lending is designed for capable borrowers who simply do not fit rigid templates. Instead of relying on automated algorithms that instantly decline unusual applications, specialist credit providers assess each scenario manually to uncover the real financial story.
- Flexible Assessment: Evaluates the overall character, history, and real capacity of the borrower.
- Beyond the Checklist: Ideal for self-employed clients lacking two years of standard tax returns.
- Solution-Oriented: Focuses on finding viable pathways to approval rather than searching for reasons to issue a rejection.
Non-conforming is a spectrum rather than a single product. At one end sits near prime lending, for borrowers who fall just outside standard criteria on one or two points. Further along, Specialist and Specialist Plus cover more significant credit histories and complex structures.
Mainstream Lenders vs Specialist Lenders: Understanding the Divide
Mainstream credit providers rely on highly automated systems requiring spotless credit and standard employment. Conversely, specialist lenders focus on individual circumstances, dedicating human expertise to manually evaluate complex files that traditional automated systems cannot process.
| Feature | Mainstream Financial Institutions | Specialist Lenders (e.g., VMG) |
|---|---|---|
| Assessment Method | Automated algorithm and rigid credit scoring. | 100% manual underwriting by human credit analysts. |
| Income Verification | Strict standard documentation (2 years ITRs minimum). | Flexible alternative documentation (BAS, accountant declarations). |
| Credit History | Spotless record required; immediate decline on minor defaults. | Forward-looking approach; accepts past impairments and paid defaults. |
| Decision Maker | Computer systems with inflexible parameters. | Direct access to human decision-makers. |
| Target Borrower | Standard PAYG, straightforward financial situations. | Self-employed, complex income, credit-impaired, non-standard security. |
Standard Processing: Mainstream institutions demand standard residential property and zero complications.
Contextual Evaluation: Specialist lenders look beyond the surface to understand precisely why a credit issue occurred.
Relationship Focus: Specialist providers allow direct, meaningful communication between the broker and the assessor.
Lending Criteria Comparator
Select a Scenario to Compare Outcomes
Mainstream Financial Institutions
Outcome: Computer Decline
Specialist Lender (VMG)
Outcome: Considered on Merit
Indicative only. All applications are subject to Victorian Mortgage Group’s credit assessment and lending criteria.
Dispelling the Myths of Non-Conforming Finance
The most pervasive industry myth is that non-conforming borrowers are inherently irresponsible. In reality, these clients are often highly capable individuals experiencing temporary life events, structural business shifts, or unique financial situations that standard algorithms misinterpret. Here are some types of clients:
- Health and Life Events: Clients recovering from illness or navigating a divorce where finances are temporarily disrupted but are now stabilising.
- Newly Self-Employed: Capable tradespeople or professionals generating strong income without the traditional two-year tax history.
- Tax Optimisation: Business owners whose taxable income appears low due to legitimate, accountant-directed tax minimisation strategies.
- Asset-Rich, Income-Complex: Borrowers with substantial equity but non-standard or fluctuating income streams.
Why Interest Rates Reflect the Assessment Work Involved
Non-conforming loans naturally carry higher interest rates to account for the perceived risk and the intensive manual underwriting required. It is vital for brokers to frame these loans as transitional stepping stones rather than permanent financial destinations.
Intensive Underwriting: Manual assessment requires highly skilled human resources, increasing the lender’s operational costs.
Risk Premium: The flexible nature of the loan necessitates a slightly higher return to balance the broader portfolio safely.
Transitional Strategy: Borrowers utilise these loans for two to three years to establish credit or business history before refinancing to a lower rate.
Opportunity Cost: For the client, paying slightly higher outgoings now means securing a property today rather than missing out while waiting years to qualify for standard finance (see MoneySmart for general guidance on property ownership timelines).
The Non-Conforming Stepping Stone Strategy
1. Secure the Property
VMG uses manual underwriting to approve the loan. The client secures their desired property today, avoiding the opportunity cost of being locked out of the market.
2. Stabilise & Rebuild
The client makes consistent repayments. During this time, they establish their two-year self-employed tax history or rebuild their credit profile post-impairment.
3. The Exit Strategy
With a proven track record of repayments and a clean, stabilised financial profile, the broker may be able to refinance the client to a mainstream credit provider at a standard rate.
6 Client Profiles VMG Actually Helps
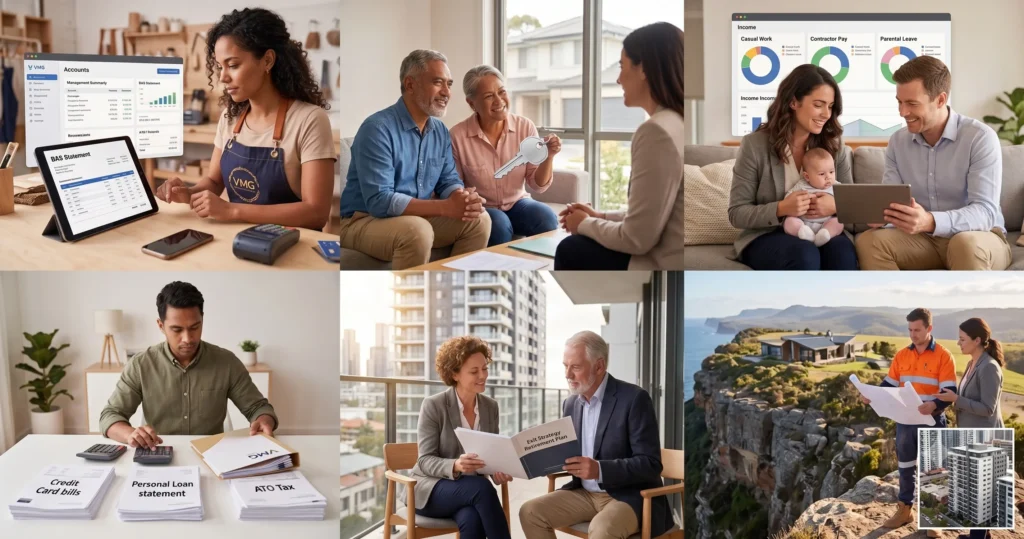
VMG provides targeted solutions across diverse borrower segments. From self-employed professionals lacking full tax returns to clients needing to consolidate complex debts, VMG delivers the flexibility that standard financial institutions simply cannot offer.
- Self-Employed Clients: We assess borrowers with just six months of ABN history, accepting management accounts and BAS statements in place of standard returns.
- Credit-Impaired Borrowers: We consider paid defaults, arrears, and discharged bankruptcies, focusing entirely on the client’s current strength and security.
- Complex Income Earners: Casuals, contractors, and those on parental leave are assessed fairly without algorithmic penalty.
- Debt Consolidation & ATO Debt: We allow the consolidation of multiple debts, including ATO tax debts (for more details on managing tax obligations, visit the ATO), into a single manageable repayment.
- Unusual Borrower Situations: Expatriates, older borrowers with clear exit strategies, and those operating within complex company structures are welcome.
- Non-Standard Properties: We offer flexibility for rural holdings, high-density apartments, and unique real estate securities.
Read the outcomes of some of our real scenarios that our BDMs have services, on our case studies page.
Broker Scenario Picker
Select your client’s hurdle to reveal the VMG solution.
Alt-Doc Solution Available
The VMG Approach: We accept newly self-employed clients with just 6 months of ABN history. We do not require two years of tax returns; instead, we can verify income using an accountant’s declaration or recent Business Activity Statements (BAS).
What Makes VMG Different?
Victorian Mortgage Group distinguishes itself as a premier Australian credit provider with over 80 years of experience, committed to genuine relationship-based lending. By removing algorithmic barriers, VMG empowers brokers to secure complex approvals swiftly.
No Credit Scoring
- No credit scoring is applied to files
- Clients with defaults are accepted
- Discharge bankrupts and Part 9 agreements are considered
Flexible Debt Ratios
- No DTI or DSR ratios are enforced
- We use a common sense approach to sensitisation
- Credit cards cleared in full monthly can be excluded from servicing
Direct Analyst Access
- Brokers get direct access to Credit Analysts
- Applications are manually assessed by our team
- Experience fast response times
Assessed Pre-Approvals
- We provide fully assessed pre-approvals
- Enjoy a flexible approach to servicing
- Applications submitted via ApplyOnline® & DocuSign®
Dedicated BDM Support
- Contact your VMG BDM directly for more information
- Refer complex files directly to your BDM
- Benefit from fast response times on scenarios
Broad Income Verification
- Accepts newly self-employed with just 6 months ABN
- Casual, contract, and parental leave income is accepted
- Family Tax Benefit A & B and child support accepted up to age 18
The Most Important Mindset Shift for Brokers
The greatest mistake a broker can make is self-declining a deal based on traditional lending criteria. Understanding non-conforming finance means recognising that alternative pathways exist, transforming complex challenges into long-term client relationships and sustained referral business.
- Never Self-Decline: Always test a complex scenario before telling a client their goals are unachievable.
- Leverage BDM Expertise: When unsure, contact your VMG Business Development Manager to workshop the file directly.
- Focus on Solutions: Shift your perspective from rigid policy compliance to common-sense structuring and contextual assessment.
- Build Lifelong Clients: Securing a loan for a client in a difficult position creates unmatched loyalty and ongoing referral networks.
Ready to find a solution for your complex client files? Do not let a complicated scenario result in a missed opportunity. Partner with a specialist credit provider that values common-sense underwriting. Test a Scenario with our team today, or Find your VMG BDM to discuss how we can help your clients achieve their financial goals. Alternatively, explore our full suite of Broker Resources and Specialist products to discover the VMG difference.
One practical note on submission: from 2 November 2026, all VMG applications lodge through ApplyOnline and manual applications are no longer accepted. Our guide covers how to lodge with VMG and what changes.
Frequently Asked Questions
What exactly qualifies as a non-conforming loan?
How does manual underwriting benefit my client?
Why are the interest rates higher for these products?
Can self-employed clients apply without two years of tax returns?
Will past credit defaults prevent a loan approval?
*All applications are subject to Victorian Mortgage Group’s standard credit assessment and lending criteria. Terms, conditions, fees, and charges apply.